
Quick Take:
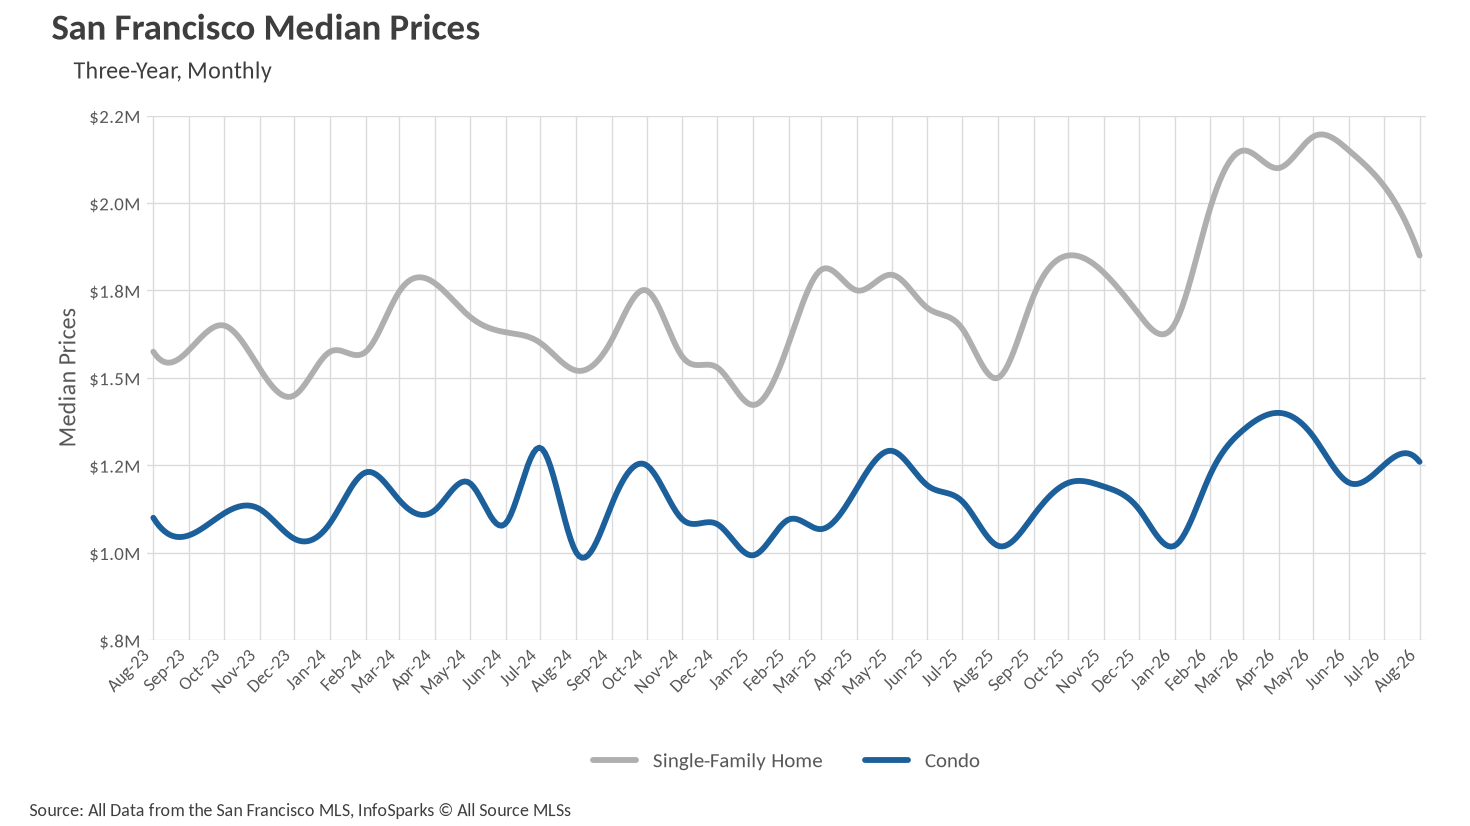
- Single-family home prices are up more than 23% year-over-year, though August’s median of $1,850,000 marks the third consecutive monthly step down from the spring peak.
- Inventory continues to tighten, with single-family listings down 33% and condo listings down more than 36% compared to last August.
- Single-family homes are selling in 13 days, while condos have accelerated dramatically to 19 days, down from 51 days a year ago.
Prices cool off from spring highs but remain far above last year
August delivered a familiar pattern for San Francisco’s single-family market: strong annual growth paired with a seasonal retreat from the spring peak. The median sale price landed at $1,850,000, a 23.33% gain over the $1,500,000 recorded in August 2025, but also the third straight monthly decline from May’s high of $2,190,000. July’s $2,050,000 gave way to a 9.76% month-over-month drop, which is typical of late-summer trading when the most competitive listings have already cleared the market.
The condo market told a quietly encouraging story. At $1,260,000, the median condo price rose 0.80% from July and climbed 23.53% year-over-year, matching the single-family market’s annual pace for the first time in recent memory. Condos have now posted three consecutive months of stability in the $1.2 million range after a volatile spring. Bidding behavior remains aggressive on the single-family side, where homes sold for an average of 22% above their original asking price, well ahead of the 12% premium recorded last August, even as that figure eased from the 26% peak seen in June and July. Condos held steady at 4% over asking, up from 3% below asking a year ago.
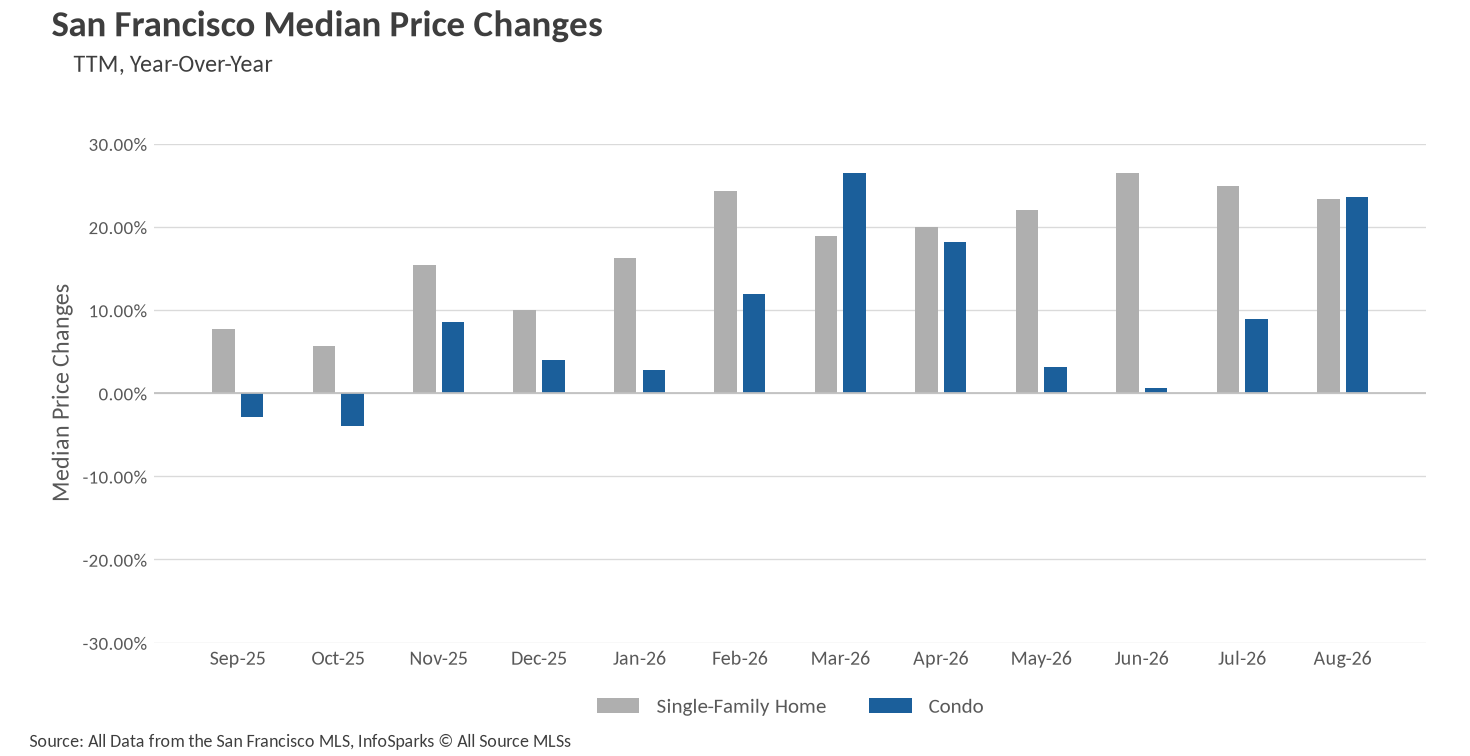
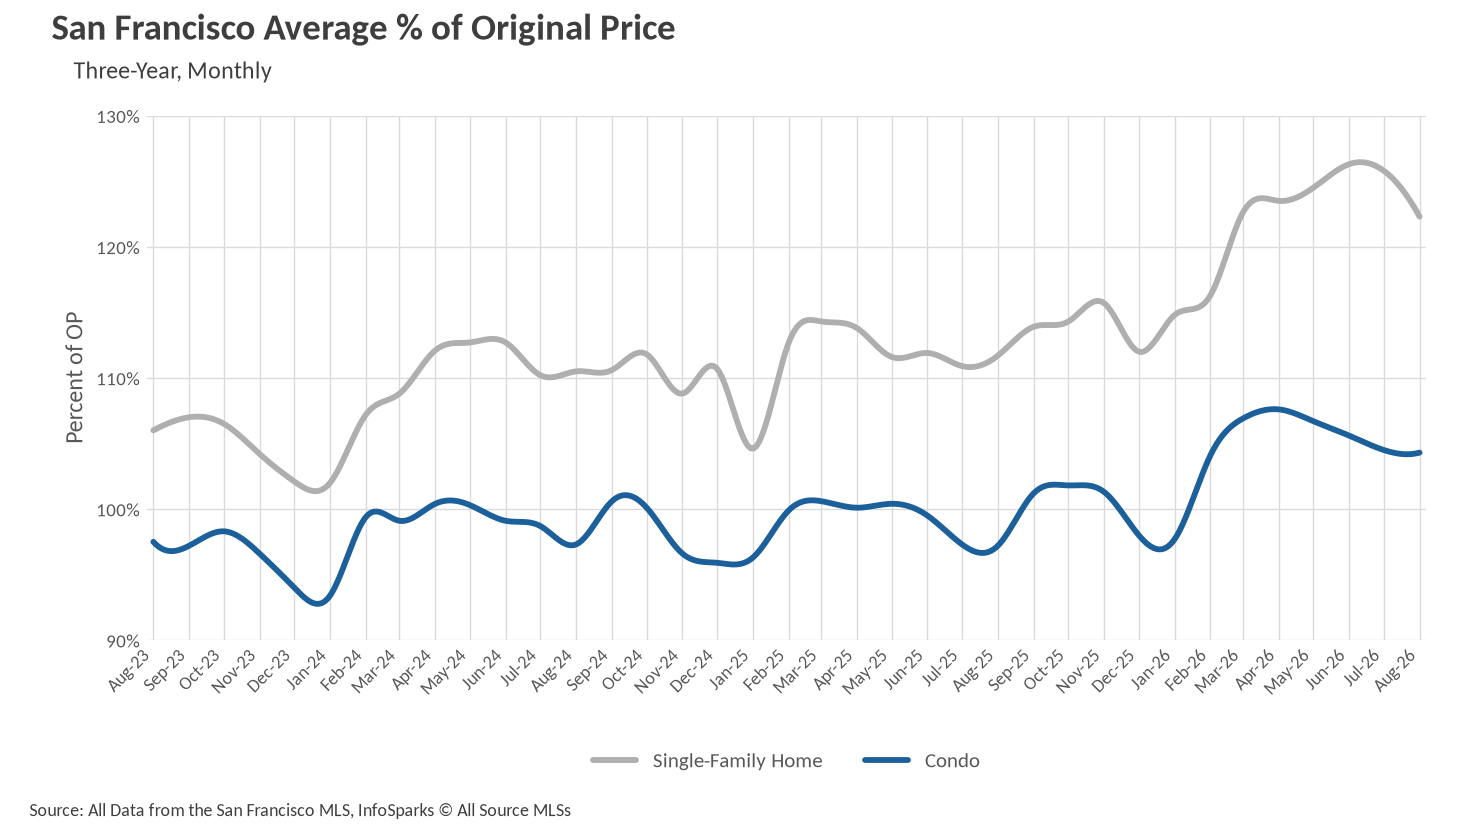
Supply keeps shrinking even as sellers return
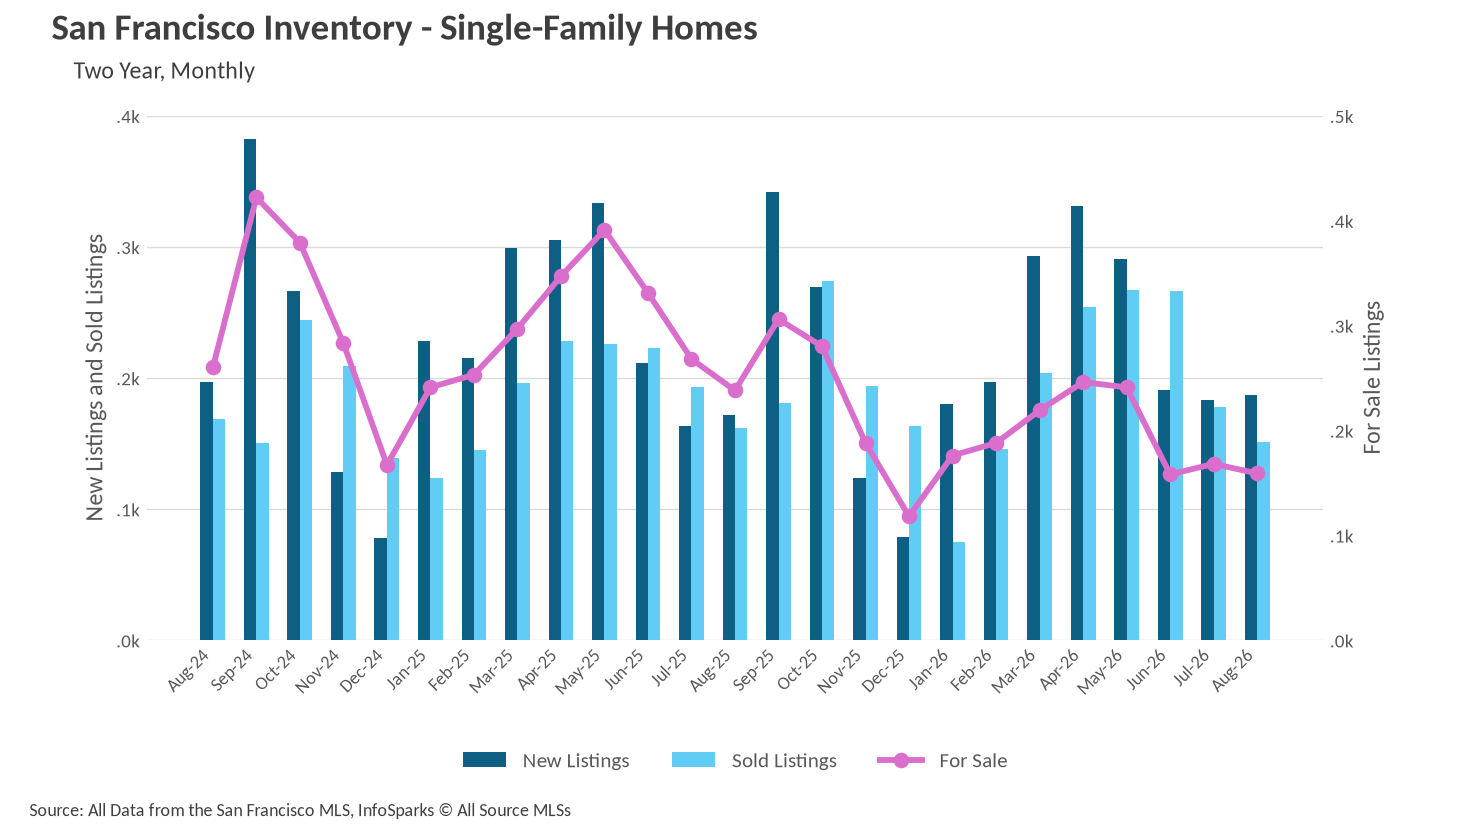
The most recent inventory reading, for August 2026, shows no relief for buyers. There were just 159 single-family homes for sale citywide at month’s end, down 5.36% from July’s 168 and down 33.19% from the 238 available in August 2025. What makes the figure notable is that sellers actually showed up: 187 new single-family listings hit the market in August, an 8.72% increase over last August’s 172. Buyers simply absorbed them faster than they arrived.
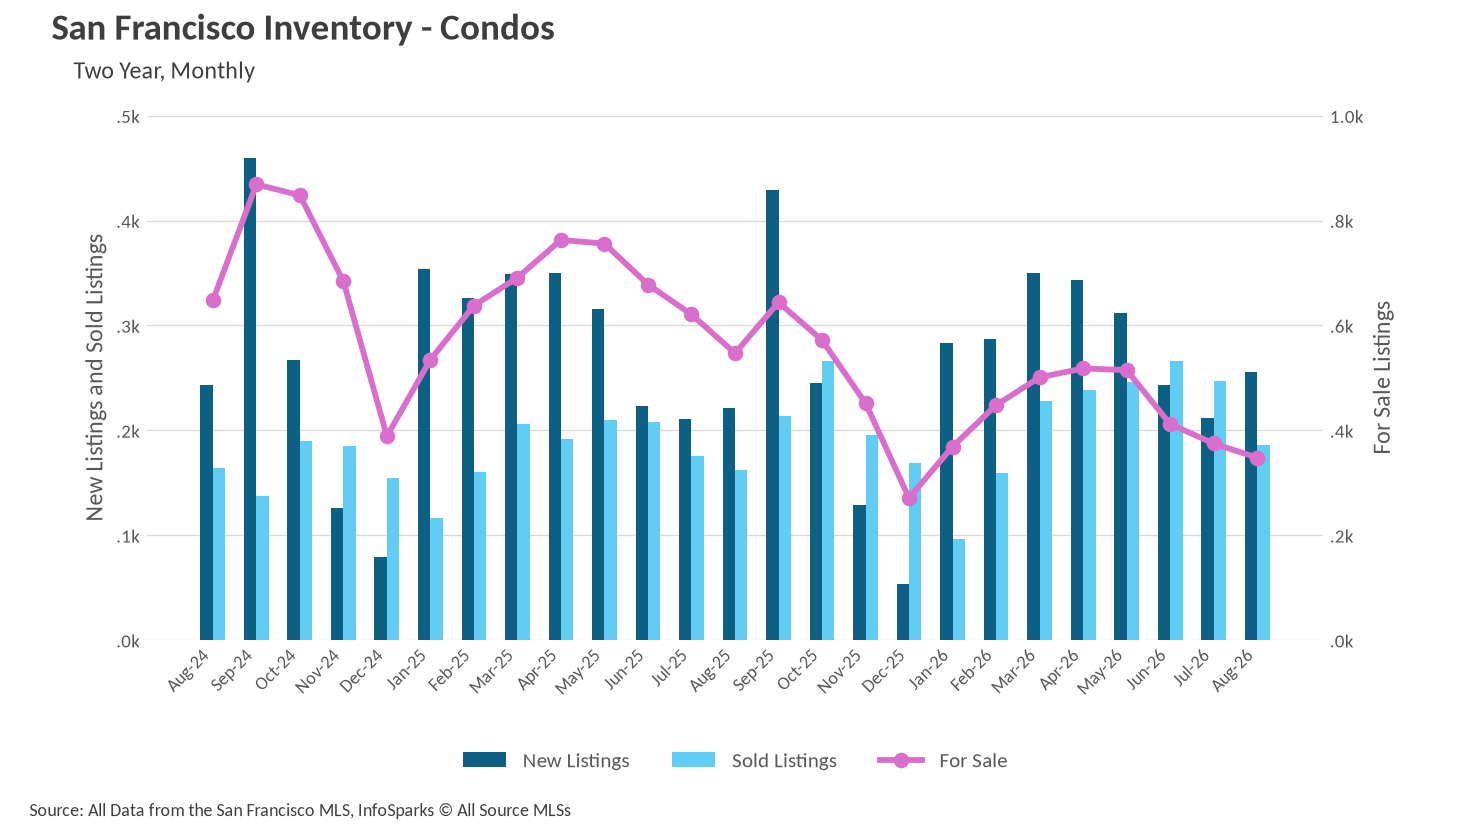
The condo picture is similar. Active condo listings fell to 348, a 7.20% decline from July and a 36.38% drop from the 547 units available a year ago. New condo listings rose 15.84% year-over-year to 256, and closed condo sales jumped 14.81% to 186, meaning the additional supply was more than met by demand. With only about 507 homes and condos available across the entire city, San Francisco’s total for-sale inventory remains at a fraction of where it stood in the summer of 2024, when more than 900 properties were on the market in August alone.
Condos have caught up to the single-family pace
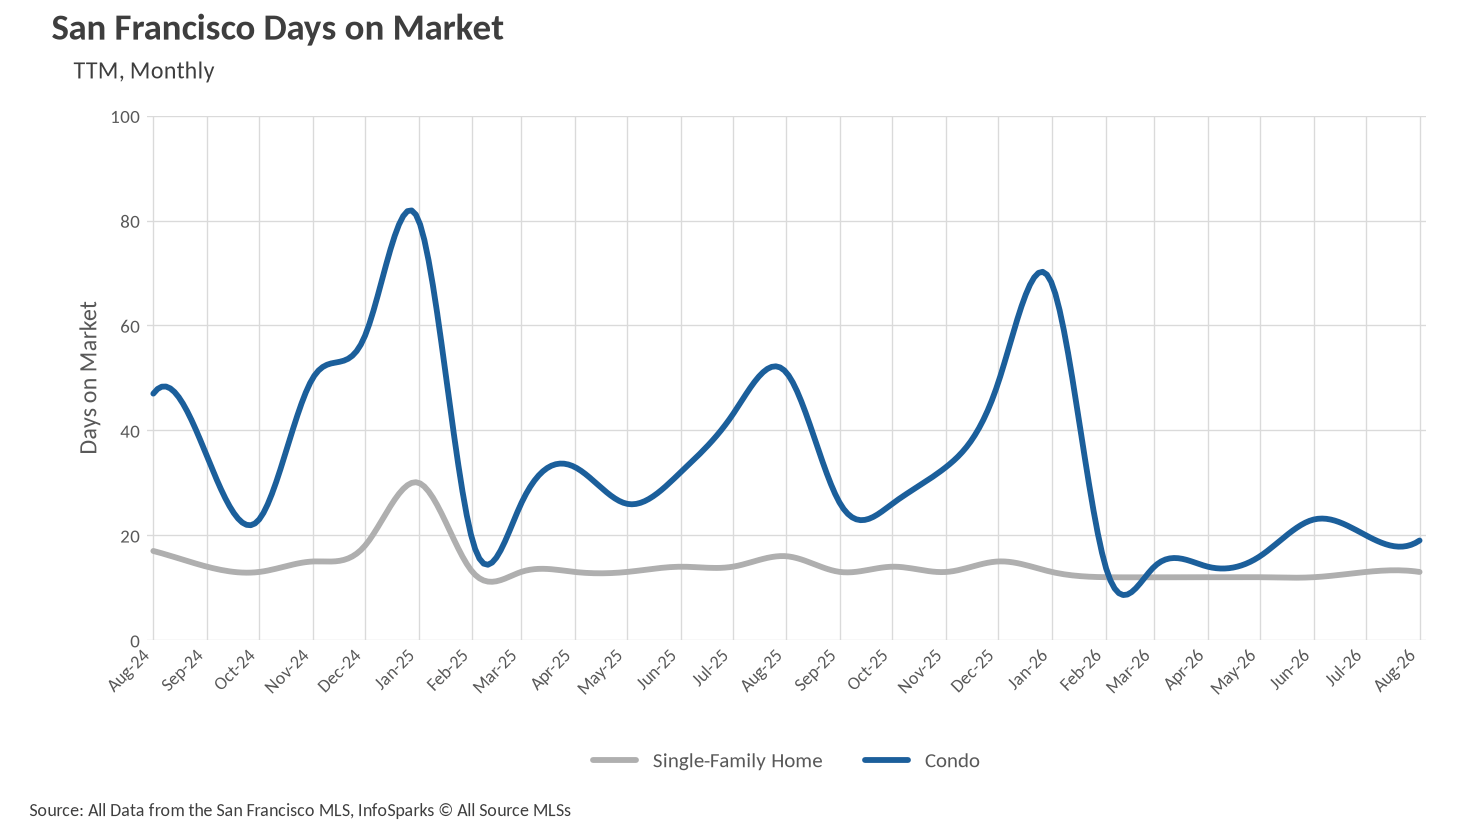
Single-family homes continue to move almost as quickly as they can be listed, spending an average of 13 days on market in August. That is a 18.75% improvement over the 16 days recorded last August, and it holds the tight 12-to-13 day band the segment has occupied all year.
The more dramatic shift is in the condo market. Condos sold in an average of 19 days in August, down from 20 days in July and down a remarkable 62.75% from the 51 days they required in August 2025. A year ago, condo sellers faced a late-summer slowdown that stretched marketing times past seven weeks. This August, they faced nothing of the kind. The gap between the two property types, which once ran five weeks or more, has narrowed to less than a week, a sign that the condo segment has genuinely re-engaged rather than simply benefiting from a quiet single-family market.
San Francisco remains a decisively seller-favored market
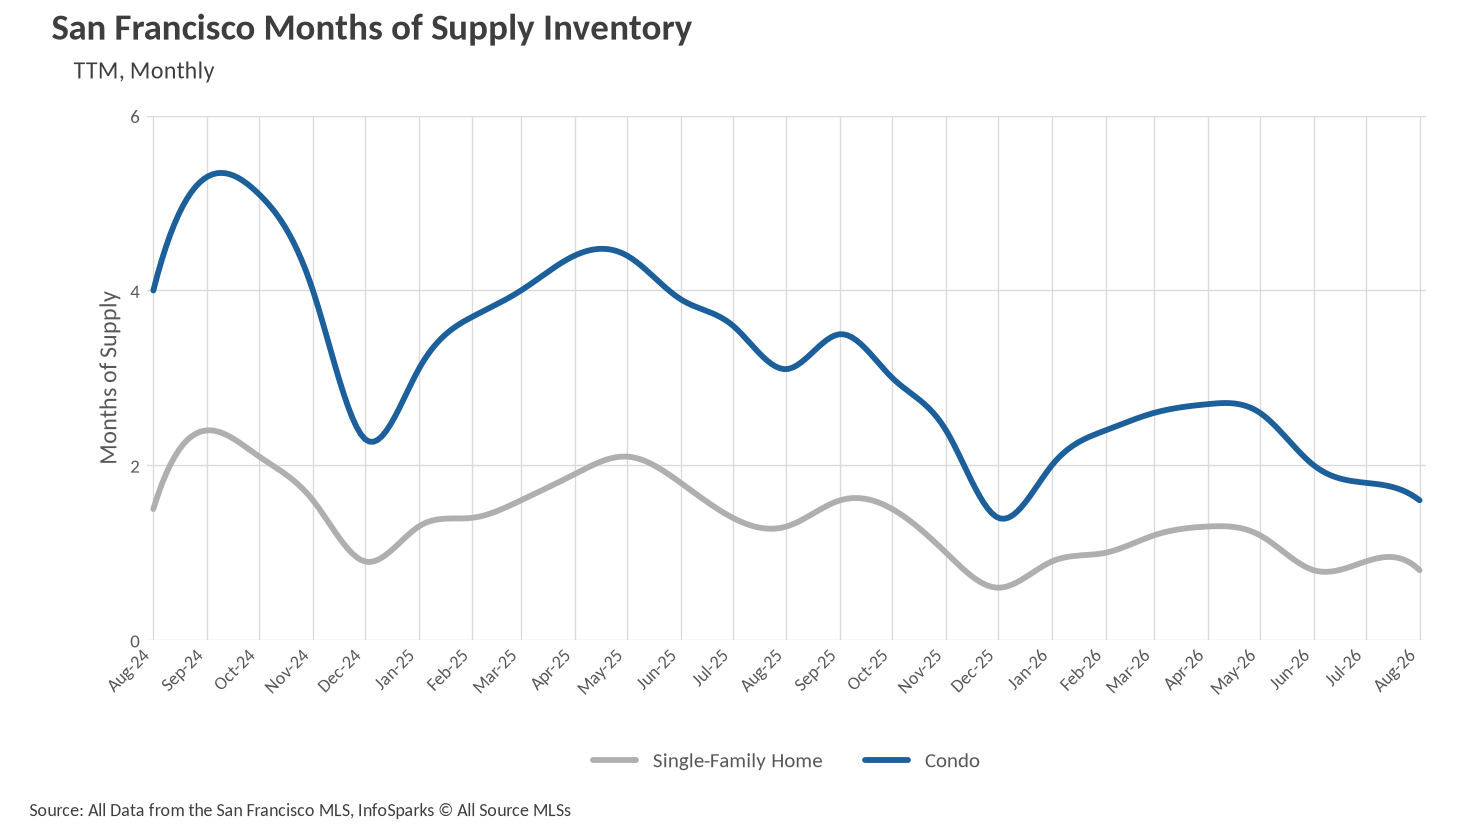
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
San Francisco sits far below that three-month threshold on both sides of the market. Single-family MSI registered 0.8 months in August, down from 0.9 in July and 38.46% below the 1.3 months recorded last August. At the current sales pace, the city’s entire single-family inventory would be exhausted in roughly 24 days. The condo segment, which was essentially balanced at 3.1 months a year ago, has tightened to 1.6 months, a 48.39% year-over-year decline and its lowest reading since last December. That transition is the single most important structural change in this market over the past twelve months: condos are no longer the buyer-friendly alternative they were in 2024 and early 2025. With supply shrinking in both segments despite rising new listings, sellers retain the clear advantage heading into the fall.
Want to know more? Our full report dives deep into the numbers. Follow us on social media @thefrontsteps for the latest market insights.
Thinking of buying or selling? Our team of experts can help you navigate the market. Contact us today for a free consultation!
Curious about market updates in other Bay Area areas? Click the button below for insights specific to the neighborhoods you’re interested in.
– theFrontSteps SFNewsletter – September 2026

Alexander Clark
theFrontSteps Real Estate
Top 1% SF Agents
Founder theFrontSteps
DRE# 01339386
@theFrontSteps
415-254-5351
[email protected]

“Alex is, simply put, the best real estate agent in San Francisco. In a span of a few years, Alex has helped us buy two homes, and sell another two. Most of those deals presented unusual, and daunting challenges–financing problems…” Continue Reading